BOSTON UNIVERSITY · PROPERTY + INSURANCE

Know what to verify before you insure the home.

For a parent buying near BU, insurance starts with the property: building type, association documents, occupants, financing and the plan after graduation. Keep those facts together before a licensed insurance professional quotes the policy.

BU property-firstInsurance follows the home and ownership plan.
Massachusetts-sourcedCore insurance sources refreshed 2026-09-20.
Clear professional rolesReal estate, lending and insurance stay separate.

WHAT ARE YOU DOING?

Most BU insurance decisions start with the ownership plan.

The parent-buyer path is primary. Renting, future-landlord use and investment are supporting paths—not four equal experiences competing for attention.

PRIMARY PATH · PARENT BUYER

Buying a home for your BU student

Match the association documents, actual occupants, lender requirements and post-graduation plan before you rely on a unit-owner quote. If roommates will pay rent, disclose that use rather than assuming a standard owner-occupied scenario covers it.

RENTER

Renting near BU

Confirm belongings, liability, roommate treatment, loss of use, exclusions and the effective date.

See renter answers →
AFTER GRADUATION

Keeping the home as a rental

Changing occupants or collecting rent is a reason to re-review the policy and building rules.

Plan hold vs. sell →
INVESTOR

Operating the property

Separate the owner’s property coverage questions from each tenant’s belongings and liability.

Review underwriting →

CONDO / CO-OP DUE DILIGENCE

Read the building documents and the unit policy together.

For a condominium, Massachusetts guidance separates association coverage from unit-owner coverage. The actual policy, certificate, governing documents and deductible schedule control the boundary.

BUILDING / ASSOCIATION

Master policy or building insurance

Request the applicable insurance certificate or policy information, deductibles and the governing documents that describe what the association or building is responsible for.

UNIT / OWNER

HO-6 or other property-specific coverage

Have the licensed insurance professional identify what the owner still needs to insure, including interior property, belongings, liability, loss of use and applicable assessment exposure.

Do condo dues mean the unit is already fully insured?

No. Massachusetts DOI explains that the condominium association master policy and the unit owner’s HO-6 policy cover different responsibilities. Obtain the master-policy information and relevant association documents, then have the licensed insurance professional identify what the unit owner still needs to insure. Do not infer full coverage from an HOA-dues line.

Massachusetts DOI source ↗

ATTACH INSURANCE TO A HOME

Choose a BU-area property. Get the questions for that property type.

No street address is shown here. Open the CH2 property workspace when you are ready to review the exact listing and keep the selected home attached to Frank.

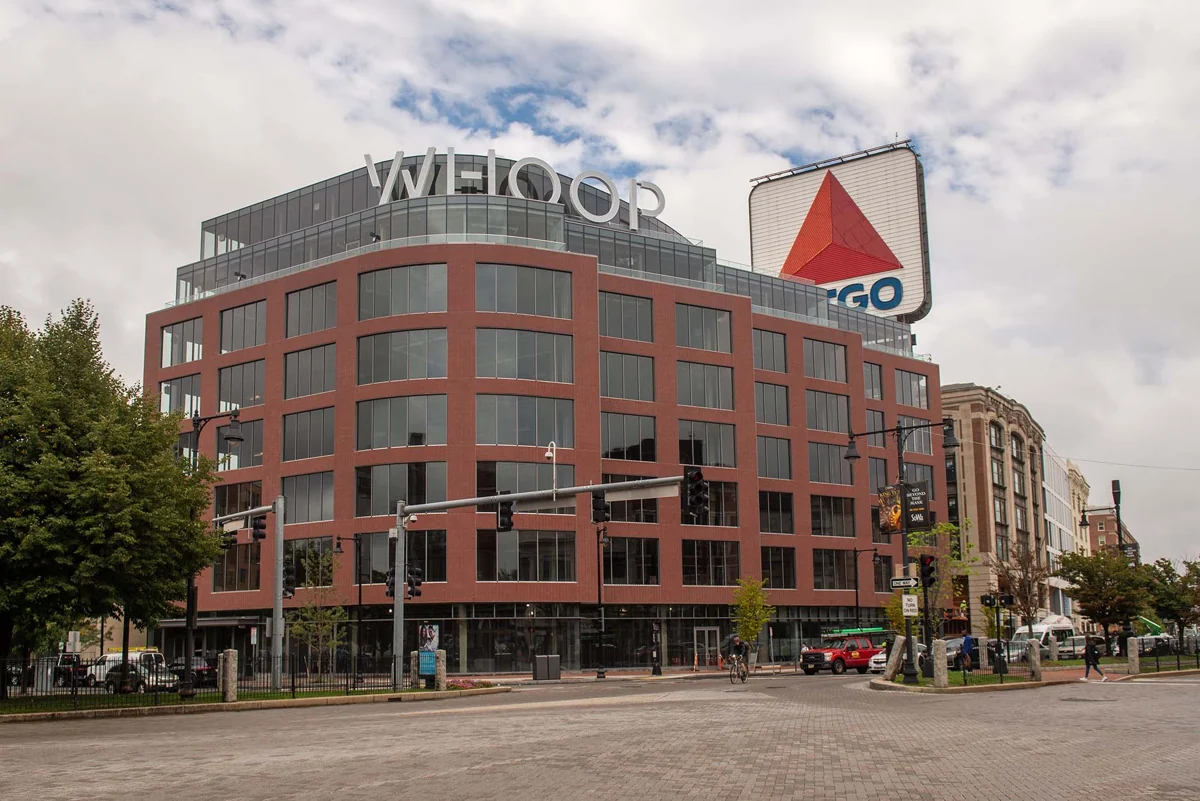
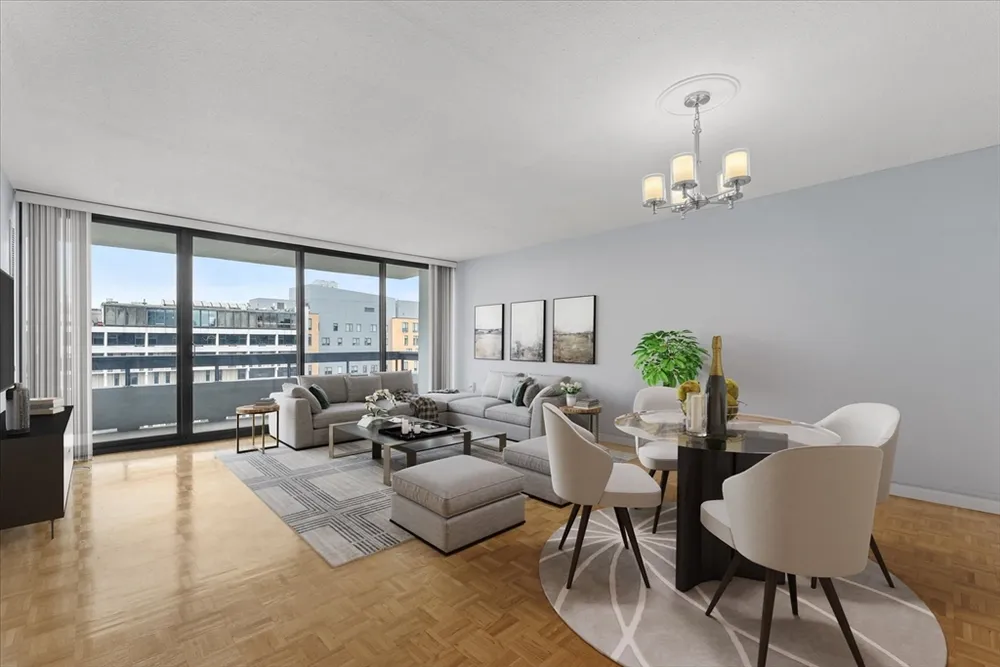
Co-op property in Fenway near Boston UniversityFenway · 0.4 miles to BU*

Co-op · $579,000

Insurance review for this property type

  • Building or association insurance documents and the ownership / occupancy responsibilities for the unit
  • Who will own and occupy the home, including the BU student and any unrelated roommates
  • Whether anyone will pay rent now, over the summer, or after graduation
  • Flood, surface-water, sewer / drain-backup, and below-grade questions for the exact address
  • The lender’s insurance evidence requirements and the policy effective date, if financing
  • What needs to be re-reviewed if the occupants or use of the property changes

These are questions to verify—not coverage conclusions. The actual address, association documents, insurer and policy control.
*Campus distance comes from the existing CH2 BU inventory record. Listing availability and price can change; verify the current property record before relying on it.

KEEP THE SAME PROPERTY ATTACHED

Frank leads the property side. Financing and insurance support it.

One property can move through three professional conversations without asking any one professional to act outside their role.

Frank Carroll
BU REAL ESTATE · PROPERTY + CONDO DOCUMENTS

Frank Carroll

Use Frank for the property, neighborhood, offer process and condo / co-op document questions. When you select a home above, the property can travel into Frank’s existing CH2 request instead of starting over.

Work with Frank
Matt Dean
FINANCING SUPPORT

Matt Dean

Organize the financing scenario and confirm the state-appropriate licensed originator before a Massachusetts application.

Review financing →
POLICY + QUOTE

Massachusetts-licensed insurance professional

Confirms coverage, exclusions, limits, deductibles, effective date and price for the actual property.

Verify a Massachusetts license ↗

Role boundary: Frank provides real-estate guidance. Matt provides financing planning and state-appropriate lending routing. A Massachusetts-licensed insurance professional confirms the policy and quote. CollegeHousing.ai keeps the property facts connected; it does not replace those professionals.

DIRECT ANSWERS

Four questions that change the BU housing decision.

These answers are visible in the page—not hidden behind a second search box or a wall of accordions. The full research library remains available when someone wants deeper detail.

Do condo dues mean I already have all the insurance I need?

No. Massachusetts DOI explains that the condominium association master policy and the unit owner’s HO-6 policy cover different responsibilities. Obtain the master-policy information and relevant association documents, then have the licensed insurance professional identify what the unit owner still needs to insure. Do not infer full coverage from an HOA-dues line.

Does one renters policy cover all my roommates?

Do not assume it does. Massachusetts DOI advises roommates to research whether a policy can be purchased together and notes that, outside certain household definitions, separate coverage for adult tenants may be appropriate. Confirm the named insureds, shared limits and carrier rules for the actual household.

What should I bring when requesting an insurance quote?

Prepare the property address, ownership and occupancy, move or closing date, desired limits and deductibles, and relevant condominium master-policy details. If there is financing, bring the lender’s insurance requirements. Use the insurer’s secure quote process for sensitive information and verify Massachusetts licensing before relying on the policy.

Open the full BU insurance research libraryCore insurance sources refreshed 2026-09-20.

NEXT IN THE BU HOUSING JOURNEY

Keep insurance attached to the home—not floating beside it.

Browse the property, carry the same home into Frank’s diligence process, coordinate financing, then verify the policy with a Massachusetts-licensed insurance professional.

CollegeHousing.ai is independent of Boston University. This page provides educational housing and insurance-planning information, not an insurance policy, quote, coverage determination, legal opinion or lending approval. A Massachusetts-licensed insurance professional must confirm coverage, exclusions, limits, deductibles, price and effective dates for the actual property. Flood, condo and lender requirements are property- and policy-specific.