DIRECT ANSWER
For a condo in Boston, the City’s First-Time Homebuyer Program offers income-eligible buyers a grant toward the purchase, and Boston’s housing office requires you to buy a one- to three-family home or condominium in Boston as your primary residence. You’ll also need first-time buyer status, Homebuying 101, participating-lender pre-approval, and the program’s income and asset limits.
WHAT TO VERIFY NEXT
Move from the answer to the actual decision.
Confirm the condo is in Boston and will be your primary residence.
Check whether you are a first-time homebuyer under the City’s three-year rule.
Complete a CHAPA-approved Homebuying 101 class.
Get pre-approved by a participating mortgage lender.
FINANCING · RUN THE NUMBERS
Test the full BU ownership scenario before choosing a financing path.
Use the same current BU benchmarks and property context as the approved BU housing-cost decision engine. Replace planning assumptions with exact property and borrower figures before acting.BUILD YOUR BU HOUSING PLAN
Put your numbers into the decision.
$4,551 principal + interest at 6.95% + $200 modeled property/operating costs.
Renting uses about $110,304 over 4 years. This ownership model uses about $4,751/month of cash flow and pays down about $31,391 of mortgage principal. With a 0% annual home-value assumption, gross equity is about $203,277 before transaction costs.
Not complete yet: add the exact property taxes, condo/HOA and maintenance assumptions before treating this as a serious rent-versus-own comparison.


Saved plans stay on this device. A shared link includes the planning assumptions shown here, but not your name, email, phone or income.
The model excludes buyer closing costs, selling costs, utilities, tax effects, repairs outside the entered reserve and other property-specific charges. Mortgage math uses the current Freddie Mac 30-year benchmark shown on this page; it is not a rate quote. Investor DSCR is illustrative only and does not represent a lender underwriting decision.
FINANCING JOURNEY · HOUSING CONTEXT
See the property context behind the financing decision.
FINANCING JOURNEY · CURRENT PROPERTY CONTEXT
Compare current BU-area homes in the approved workspace.
Test the complete monthly picture, compare current BU-area homes, and carry the same scenario into a financing review.Homes near Boston University
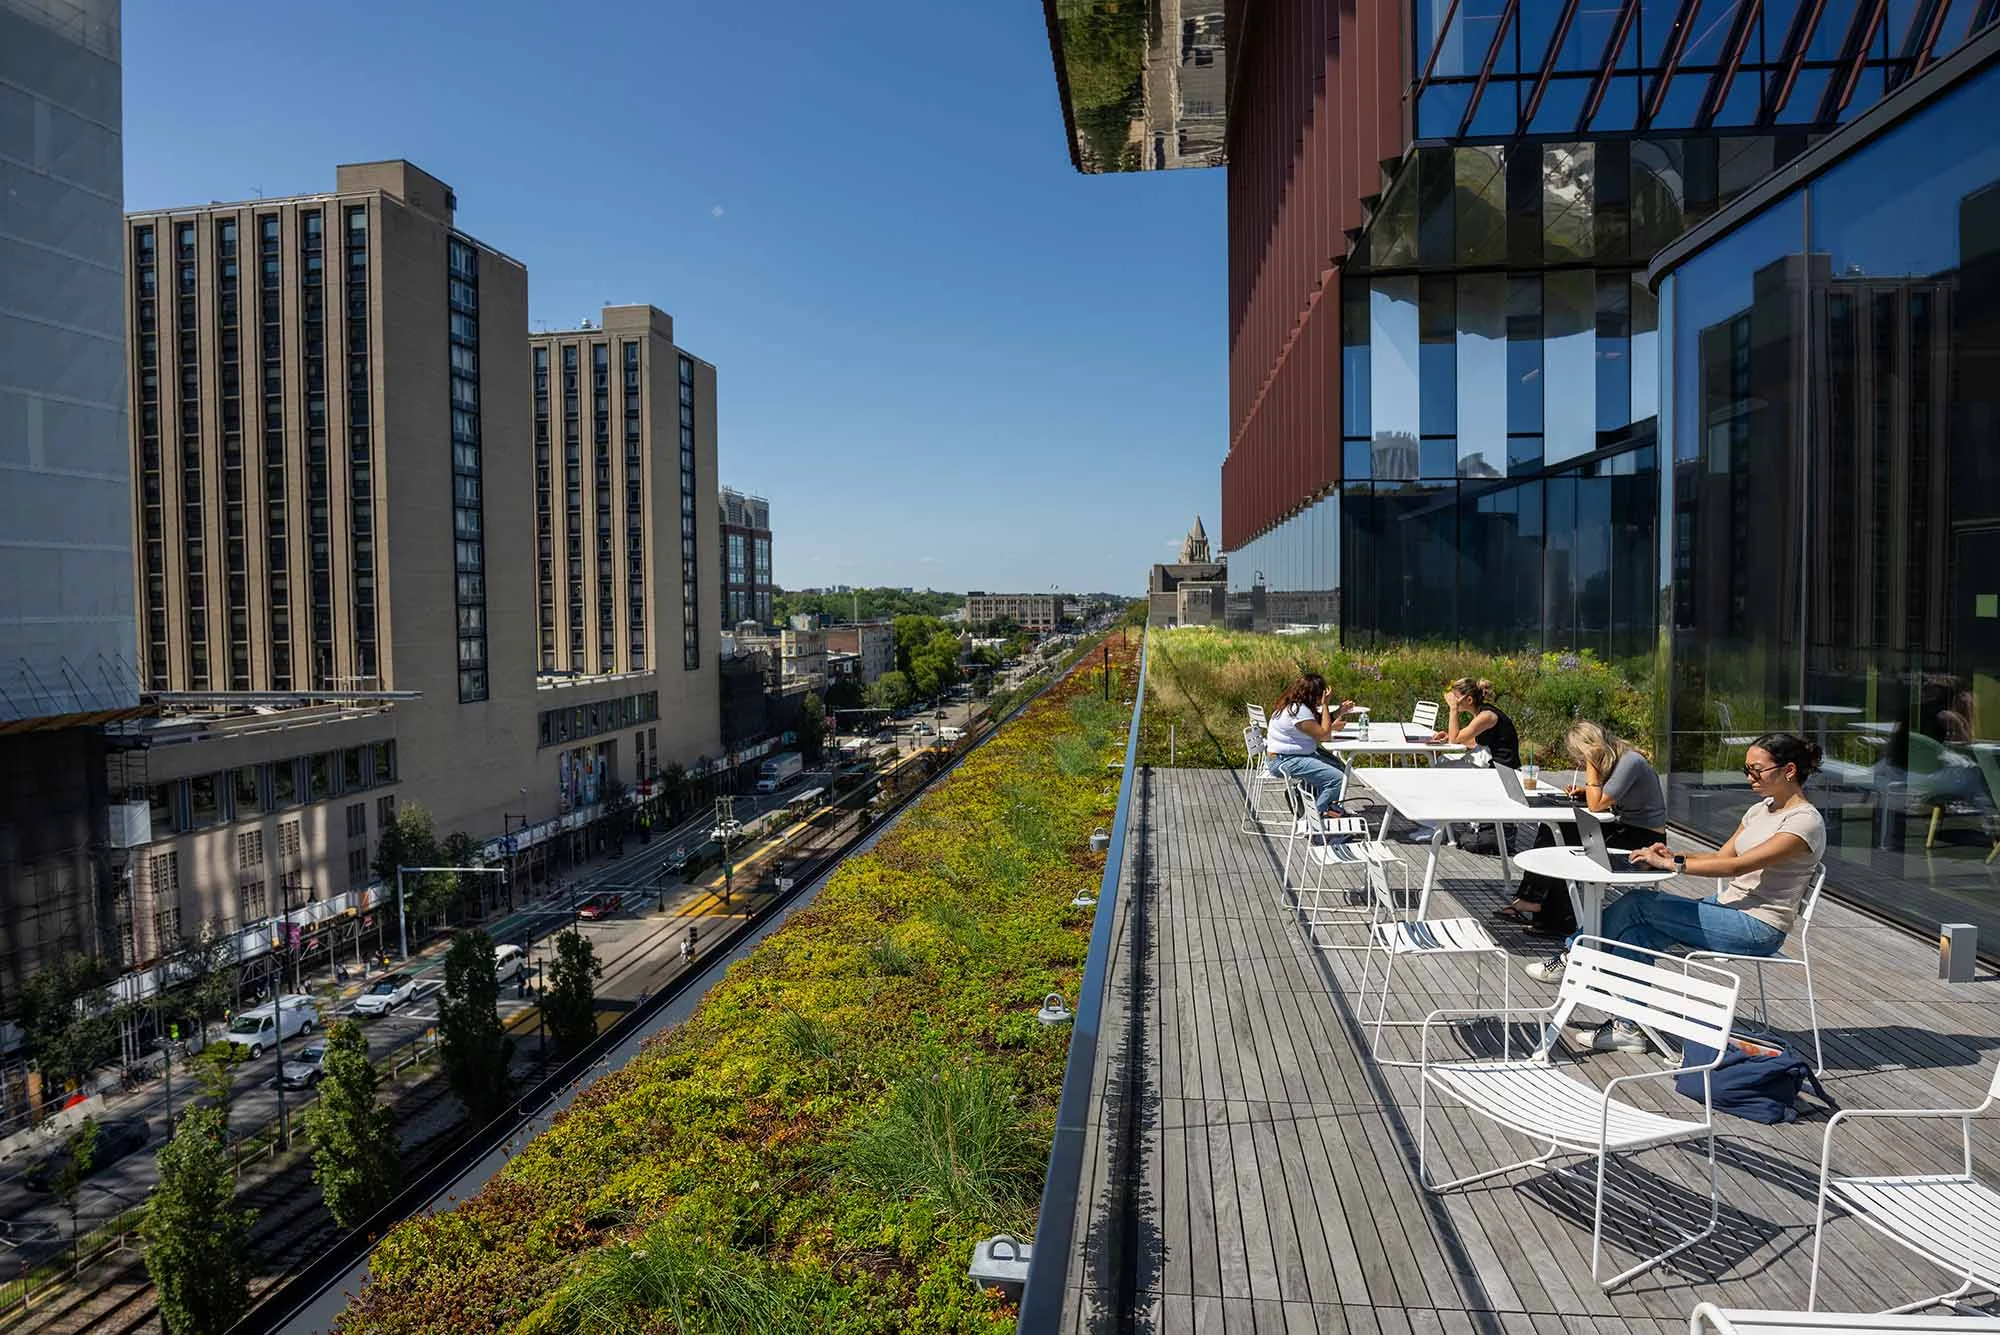
Compare campus proximity, ownership costs and the four-year numbers — not just listing prices.
Fenway · 0.4 miles to BU · 8 min walk
Current published selection. Confirm prices and availability. Distances are straight-line to campus.
Work with local experts
Get guidance from professionals who know BU and the surrounding neighborhoods.
FINANCING JOURNEY · PROFESSIONAL REVIEW
Bring the same BU scenario into the conversation.
The appointment request opens here with the correct professional preselected, so the housing question does not have to be rebuilt from scratch.FINANCING JOURNEY · NEXT STEPS
Keep comparing the same BU housing plan.
DETAIL 01
What financing is available for a BU-area condo?
Boston’s First-Time Homebuyer Program can help if you’re income-eligible and buying a condominium in Boston as your primary residence. The City says assistance is a grant for Boston residents and a 0% interest deferred loan for non-Boston residents.
- If your household income is under 100% of AMI, the grant is 3% of the purchase price, up to $50,000, plus closing costs if applicable.
- If income is between 101% and 135% of AMI, the grant is 2% of the purchase price, up to $35,000.
- If the condo is deed-restricted, the grant amount is 2% of the purchase price.
DETAIL 02
Who qualifies and what you must do first
To qualify, you need to be a first-time homebuyer, complete a CHAPA-approved Homebuying 101 class, get first-mortgage pre-approval from a participating lender, and meet the City’s income and asset limits. Boston also says the home must be your primary residence.
- The City defines first-time homebuyer as someone who has not owned a property in the past three years.
- Assets must be under $100,000, and applicants may be found ineligible if there is no demonstrated need based on household assets.
- The mortgage loan must adhere to Fannie Mae general loan limits.
DETAIL 03
What to expect in the process
Boston says the Homebuying 101 class is required, and the city also offers homeownership drop-in sessions for personalized support. The application process starts with reading the program details, reviewing the checklist, and completing the class before moving ahead with the rest of the application.
- Plan on using a participating mortgage lender; the City does not require one specific bank.
- The City’s housing office is the place to confirm current program details and start the application.
- If you are looking at an income-restricted condo, Boston says the buyer must use arms-length financing, meaning a bank or mortgage company, not a friend, family member, or private source.
Sources, freshness and verification
These sources were checked for this answer on September 13, 2026. Time-sensitive costs, program rules, lease terms and property conditions should be reconfirmed before acting.
ASK THE NEXT BU QUESTION
Keep the answer in context.
Ask the next question about the same BU housing decision instead of returning to a generic search.
Ask a question to get the answer first. CH2 opens a tool or broader page directly only when you ask to use or view it.